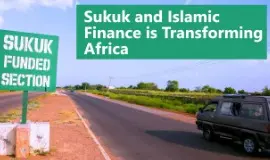
Sukuk instruments are increasingly financing critical infrastructure projects across the African continent while simultaneously contributing to socially useful and economically impactful ventures. As African nations grapple with infrastructure deficits and the persistent challenge of transparent capital utilization, Islamic finance instruments—particularly those issued in local currencies—are carving out a vital role in reshaping the developmental landscape.
The momentum behind these financial instruments is evident in market demand and tangible project delivery. A prominent example occurred with a local currency issuance valued at 100 billion naira, which was heavily oversubscribed by eager investors looking for secure, asset-backed opportunities. Building upon this market appetite, the Federal Government of Nigeria has repeatedly turned to the sukuk market, issuing a series of sovereign instruments designed specifically to bridge the country’s infrastructure gaps. The proceeds generated from these specific issuances have been channeled directly into the construction, rehabilitation, and completion of 28 major road projects across Nigeria, connecting vital economic corridors and easing transportation bottlenecks for citizens and commercial enterprises alike.
Unlike conventional debt instruments, the operational mechanics of sukuk offer distinctive structural safeguards that appeal to both governments seeking accountability and investors prioritizing security. Financial expert Hassan Usman outlines the fundamental reasons why sukuk provide greater regulatory compliance and leave virtually no room for corruption or the illicit loss of public funds when compared to traditional sovereign bonds.
The core distinction lies in the intrinsic design of the financial instrument. A sukuk project must be executed precisely as intended for the direct benefit of the public, such as establishing a critical transportation artery like a road or constructing an educational institution like a school. Once the tangible asset is completed, it is typically leased, allowing revenues—such as road tolls or facility usage fees—to be generated and subsequently returned to the investors as yields.
In contrast, traditional bonds operate fundamentally as general government debt. With conventional borrowing, even if the raised capital is mismanaged, wasted, or lost to bureaucratic inefficiencies, the government remains legally obligated to repay the principal and interest to bondholders, often leaving behind no tangible infrastructure asset or developmental gain to show for the debt burden. Sukuk fundamentally alter this risk profile because the funds raised cannot be diverted for any other purpose outside of the explicit mandate for which they were gathered. The rigid, asset-backed nature of the structure ensures that capital is inextricably linked to physical, verifiable development on the ground, providing an inherent barrier against fund diversion and fostering a transparent environment where public infrastructure and investor returns advance hand in hand.